

Regions Bank
4.4

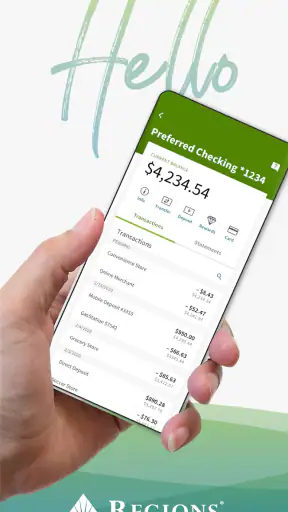
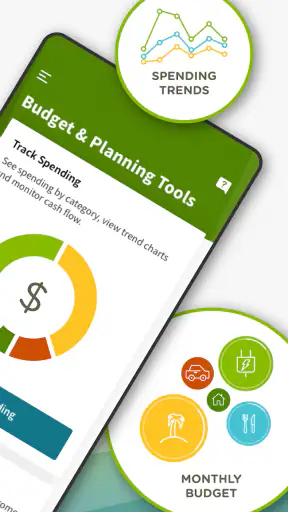
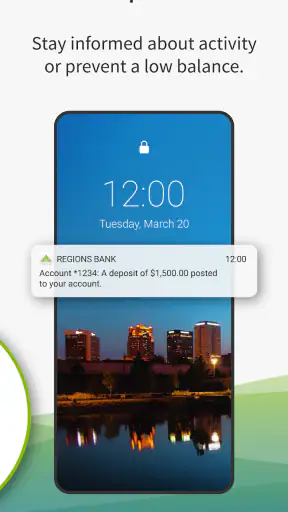
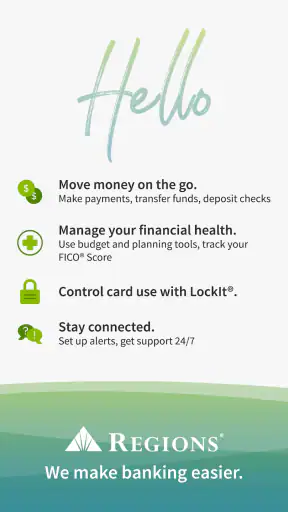
I approached Regions Bank as an everyday mobile banking app, not as a financial planning platform or a replacement for every money tool on a phone. That distinction matters. The app is made by Regions Bank, is free to use, and is aimed at people who already bank with Regions and want regular account access without relying on a desktop browser or a branch visit.
My main question was simple: does it make routine banking less troublesome? For checking balances, keeping an eye on activity, and handling basic account tasks while away from a computer, it fits naturally into a daily routine. It is available for everyone from an age-rating perspective, and its long presence in the finance category gives it the feel of an established banking companion rather than a new experimental service.
The app has a 4.4 average from around 128 thousand ratings, with more than 5 million installs. Those figures do not tell me whether every customer will enjoy it, but they do suggest that Regions customers commonly use it as part of their banking routine. I would judge it less by the headline numbers and more by whether its workflow matches the way you already manage money.
What I would check before choosing it
Before settling into a routine, I would check whether the app fits the way I actually access my Regions accounts, rather than assuming a phone-based option will suit every situation. I’d also consider how I handle unusual account questions and whether I want a separate tool for broader money planning. That quick personal check helps clarify what I expect from it over time.
The first decision is whether you already use Regions
The most important filter is not the interface. It is your relationship with the bank. If your accounts are with Regions, the app has an obvious purpose: it brings your banking activity into one place and reduces the need to open a browser or contact support for ordinary checks. If you do not bank with Regions, installing it will not make it a general-purpose money manager. It is a bank-specific tool, so its value depends on being part of that institution’s customer ecosystem.
This is where it differs from budgeting apps and digital wallets. A budgeting app may gather information from several institutions, while a wallet is usually centered on payments and cards. Regions Bank is more focused on the relationship between you and Regions. I would therefore decide first whether I need direct access to a Regions account or whether I am actually looking for a broader view across multiple banks.
Think about the tasks you repeat every week
I find banking apps most useful when they remove small interruptions. Checking whether a payment has cleared, looking at recent activity before making a purchase, or confirming that money arrived can all be easier from a phone than from a laptop. These are not dramatic features, but they are the moments that determine whether an app becomes a habit.
A useful test is to list the banking actions you perform most often. If those actions are ordinary account checks and routine management within Regions, this app is a sensible candidate. If your priority is detailed household budgeting, investment research, or a complete picture of accounts held at different institutions, I would compare it with tools designed specifically for those jobs instead of expecting a bank app to cover everything.
Device compatibility should be part of the decision
The current version is 8.7.0.1, and the app requires iOS or Android version 11 or later. That is worth checking before you plan a switch, particularly if you keep an older phone for banking or use a device that no longer receives operating-system updates. A free download is only useful if the phone you depend on can run it reliably.
I also treat a banking app differently from a casual finance calculator. The phone itself becomes part of the access experience, so a supported operating system, a working screen lock, and a device you can keep updated are practical considerations. If your phone is too old for the minimum requirement, the browser or another access method may be more realistic than replacing the device solely for this app.
Security habits still belong to the user
Using a bank app does not remove the need for sensible account habits. I would install it only from the official app marketplace, keep the phone’s operating system current, and avoid signing in on a device shared with other people. I would also pause before approving an unfamiliar sign-in or transaction prompt rather than treating every notification as routine.
That advice is not a criticism of Regions Bank. It is simply the trade-off of putting convenient account access in your pocket. The faster it is to check money, the more important it becomes to protect the device and the sign-in details that make that access possible.
What the public reception tells me
The app has around 22 thousand written reviews, alongside its larger rating total. I see that as useful context rather than a guarantee. A strong average can indicate that the everyday experience works for many people, but banking reviews often reflect individual account situations, device differences, and moments when a customer needs help. I would use the rating as a confidence signal, not as a substitute for checking whether the app suits my own banking needs.
Where Regions Bank is most convincing
The strongest case for the app is convenience within one bank. When I want a quick view of my relationship with Regions, a dedicated app is usually more direct than navigating a general financial service. The context is already centered on the bank I use, so I do not have to turn a broad money dashboard into a banking session.
That focus can also make the app easier to explain to someone who does not want a complicated financial setup. A person who mainly wants to stay aware of account activity may prefer a bank-branded app over a separate budgeting service with many categories, charts, and connected accounts. In that situation, simplicity is not a lack of ambition; it is the reason to choose the product.
The app’s free price also removes one common barrier. I can try it without adding a subscription to my monthly expenses, which makes it easier to compare the phone experience with the usual browser or branch routine. I would still remember that “free” describes the app itself, not every possible banking service or account condition associated with the bank.
A realistic everyday workflow
Imagine I am about to pay for a large grocery order after several automatic payments have gone through. Instead of guessing from memory, I open the app, check the current account activity, and decide whether the purchase fits comfortably. Later, I can return to see whether the transaction has appeared. That small sequence is exactly where a mobile banking app earns its place: it turns uncertainty into a quick check while I am already out.
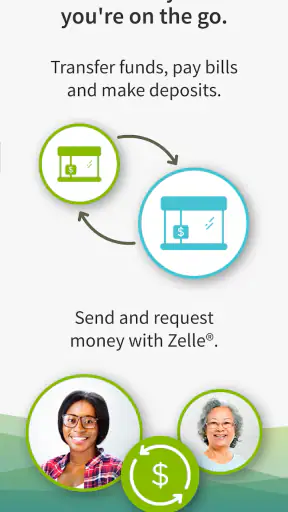
The same workflow is useful before transferring money or making a payment. I can make the account review part of the action instead of treating it as a separate chore at the end of the week. My practical tip is to use the app at decision points, not just when I am already worried about my balance. Regular short checks are more useful than opening it only after a problem develops.
It is also helpful for people who dislike financial clutter
Some money apps try to become a complete command center. That can be valuable, but it can also make a simple question feel buried under dashboards and categories. Regions Bank has a clearer role: it is the mobile doorway to Regions banking. For someone who wants fewer financial apps and does not need cross-bank analysis, that narrower purpose may feel more comfortable.
I would especially consider it for a Regions customer who travels locally, works irregular hours, or simply does not want to plan a branch visit for a basic account check. The benefit is not that a phone magically improves financial decisions. The benefit is that access becomes available at the moment a decision needs to be made.
Where alternatives may fit better
The usual alternatives fall into several categories, and each solves a different problem. A desktop banking website may be preferable when I am reviewing money for a long session, working with several browser windows, or using a larger screen. A branch or phone representative may be better when the issue is complicated, sensitive, or requires explanation rather than a quick self-service action.
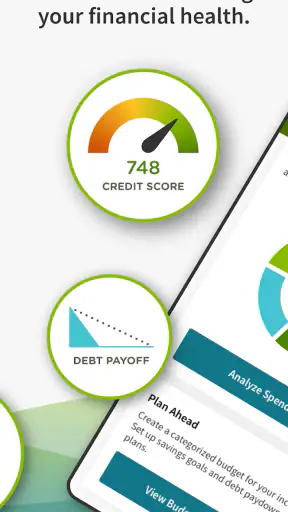
A personal budgeting app may be the better choice if I need spending categories across different banks, long-term household planning, or a combined picture of cash flow. I would not choose Regions Bank expecting it to replace a dedicated budgeting system. Its advantage is direct access to Regions, while the budgeting app’s advantage is usually broader organization across financial relationships.
Digital wallets and payment-focused apps are another separate category. They may be more convenient when the main goal is paying at checkout or organizing payment cards. A bank app is a better match when I want to look at the underlying account relationship. These tools can coexist, but they should not be judged as though they perform the same job.
Finally, a different bank’s app may be the better option if I am still deciding where to keep my accounts. In that case, the mobile experience is only one part of a larger choice involving service, account fit, and access to the institution. I would not move banks solely because one app feels more polished during a short trial. The cost of changing an established banking relationship can be much higher than the inconvenience of learning a familiar interface.
Limitations I would take seriously
The app’s bank-specific design is both its strength and its main limitation. It is not a neutral dashboard for every financial account I own. If my money is spread across institutions, I may still need another tool to see the complete picture. That creates an extra step and can make the app feel incomplete even when it works well for Regions accounts.
There is also a difference between access and financial guidance. A convenient view of account activity can help me stay informed, but it does not automatically tell me whether my spending plan is healthy or whether a larger financial decision is wise. People looking for detailed planning should be careful not to mistake a banking access tool for a full advisory service.
Mobile convenience can introduce its own friction. A small screen is fine for a quick check, but less pleasant for extended review. Typing on a phone can also be slower than using a keyboard, and a lost, damaged, or unsupported device can interrupt access. These are normal mobile trade-offs, yet they matter more when the app is part of my everyday financial routine.
I would also avoid making the app my only way to deal with urgent or unusual matters. If something looks wrong, if I need clarification, or if a request does not fit a normal self-service action, I would use the appropriate support route rather than repeatedly trying the same screen. A good banking habit includes knowing when to stop using the app and ask for help.
The cost of switching from another routine
Moving from a browser to the app is usually a small behavioral change, but it still deserves a little preparation. I would first make sure my phone meets the minimum operating-system requirement, then install the current release and confirm that I can sign in before depending on it away from home. I would keep my existing access method available until the new routine feels dependable.
Switching from a third-party budgeting app is a different matter. The app may give me direct Regions access, but it does not automatically replace the organization, history, or habits I built elsewhere. Before abandoning another tool, I would identify which tasks it handles that a bank-specific app does not. If the answer includes multi-bank tracking or detailed planning, keeping both may be more sensible than forcing one app to do two different jobs.
For a household, the transition can also involve practical coordination. Everyone who checks the account should know which access method to use and how to protect their own device. I would not share sign-in details casually just to make setup quicker. A smooth switch is one that improves access without creating a new privacy or account-management problem.
The app’s release history also matters in a modest way. It has been available since August 24, 2012, so it is not a newly launched product that needs to prove it can become part of a banking routine. That does not guarantee that every update will suit every person, but it does make the app easier to consider as an established option.
Who I would recommend it to
I would recommend Regions Bank to an existing Regions customer who wants convenient mobile access for everyday banking and prefers a focused bank app over a larger financial dashboard. It is particularly suitable for quick account awareness: checking activity before spending, keeping an eye on routine money movement, and reducing dependence on a computer for ordinary tasks.
I would also recommend trying it to someone who values a free, direct option and does not need one application to combine several institutions. The Everyone content rating makes it broadly approachable, though responsible account access still depends on the user’s device and banking relationship.
Who should choose something else
I would steer a person toward another category if their main goal is advanced budgeting across multiple banks, detailed financial planning, or payment-card organization. A dedicated service may be more appropriate for those jobs. I would also hesitate to recommend a switch to someone who is not a Regions customer, because the app’s central advantage comes from being connected to that bank.
Likewise, anyone using a phone below the required operating-system level should resolve compatibility before making the app central to their routine. If the device cannot run the current experience, a browser or another access channel may be less frustrating than trying to work around the limitation.
My final decision
My recommendation is straightforward: choose it when you want a focused mobile connection to Regions, not when you want an all-in-one financial command center. In my view, that is the fairest way to judge it. The app succeeds by making ordinary banking more reachable, and its established user base, free price, and current version make it a practical option for eligible devices.
I would install it, keep the browser available during the transition, and test it with the account checks I perform most often. If those checks feel faster and clearer, it has earned a permanent place on my phone. If I find myself needing cross-bank tracking or deeper planning every time I open it, I would use a complementary finance tool or choose a different category rather than blaming the app for having a focused purpose.
For Regions customers, that focused purpose is enough to make Regions Bank worth considering. It will not replace every financial tool, and it should not be treated as financial advice, but it can make the everyday part of banking easier to reach when I need it.
4.4
22.32K Reviews
Pros
- Mobile check deposit is convenient for everyday banking.
- Bill pay and scheduled transfers simplify routine finances.
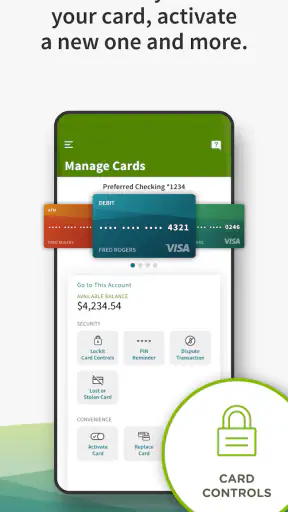
- Card controls help manage spending and improve account security.
- Branch and ATM access supports customers who prefer in-person service.
- Account alerts provide useful updates about balances and transactions.
Cons
- Some features may require an eligible Regions account or service.
- Mobile deposit limits can vary and may restrict larger check deposits.
- Fees may apply to overdrafts
- wire transfers
- or out-of-network ATMs.
- App performance and available features can vary by device and region.
- Customer support wait times may be longer during busy periods.


